The POS agent is the neighbourhood bank — treat her like one
Across Nigeria, agent banking now handles more daily cash-in and cash-out than most branches. Here's what we learned building tools for the people behind the umbrella stands.
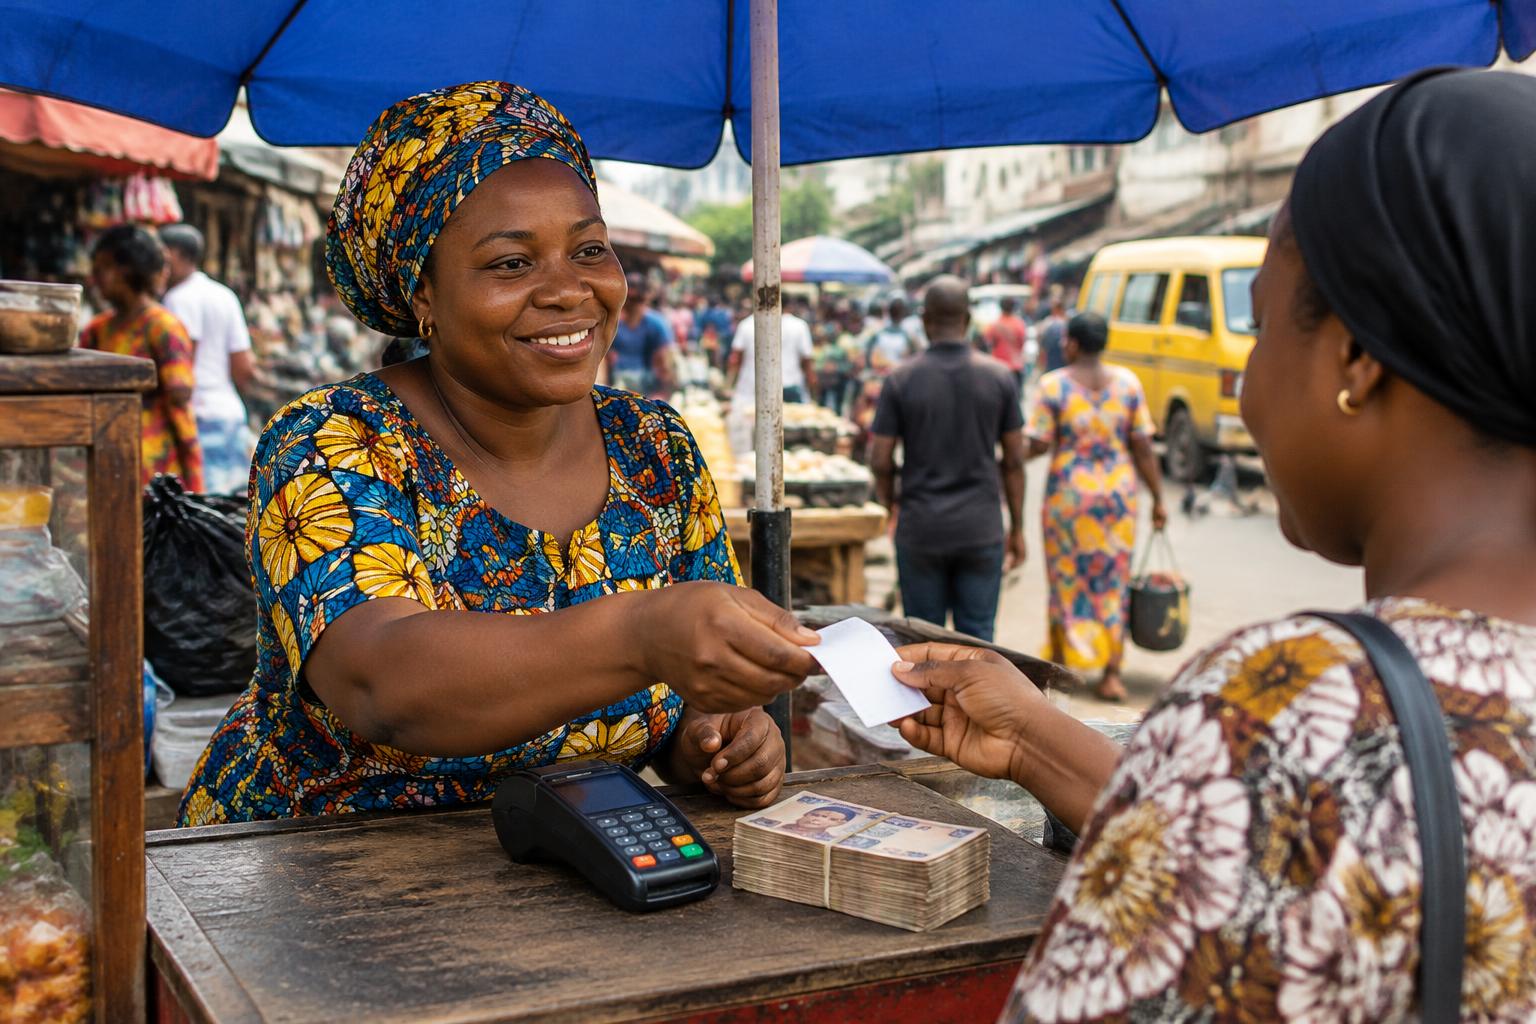
On most Lagos streets, the nearest "bank" is not a bank at all. It's a woman under a branded umbrella with a POS terminal, a ledger book, and a queue of people who trust her more than any app. Agent banking has quietly become the front door of Nigerian finance — and the numbers back it up: agents now process a larger share of everyday cash transactions than physical branches, and in many neighbourhoods they are the only financial presence within walking distance.
We spent months sitting with agents before writing a single line of code for them. What follows is what we learned — about trust, about float, and about what it actually takes to build tools the umbrella-stand economy will use.
Trust is the product
People don't queue at an agent because of the terminal. They queue because Mama Ngozi has been on that corner for six years, she knows their names, she knows which salary lands on the 25th, and when the network misbehaves she sorts it out. The terminal is interchangeable; the relationship is not. Any product built for agents that ignores this human layer is dead on arrival.
This has a practical consequence for design: agent tools should make the agent look good in front of her customers. A failed transaction that resolves itself in seconds protects her reputation. A receipt that prints clearly, every time, protects her reputation. An app that explains a chargeback in plain language protects her reputation. When we say we build for agents, that's mostly what we mean — we build for the moment she has to look a customer in the eye.
Float is the silent killer
Ask any agent what keeps them up at night and it's not competition — it's float. Running out of cash at 11am on a Saturday means turning away your best customers, and in this business a turned-away customer tries the next umbrella and may never come back. The economics are brutal: an agent's capital is finite, demand is lumpy, and every naira sitting idle in a settlement queue is a naira that can't serve the next person in line.
That's why we built instant settlement and same-day float top-ups into Pady for agents: the money from this morning's transactions should be working for you by the afternoon, not sitting in a settlement queue until Tuesday. It sounds like a small operational detail. For an agent running ₦300,000 of float through a weekend, it's the difference between a good week and a lost one.
The ledger book deserves respect — and an upgrade
Almost every agent we met keeps a paper ledger, and they keep it meticulously. It's their source of truth when networks fail and disputes arise. But a paper ledger can't reconcile itself, can't flag a duplicate, and can't answer "how did this week compare to last week?" without an hour of arithmetic on a Sunday night.
The right move isn't to abolish the notebook — it's to make the digital record so reliable that the notebook becomes a backup instead of the system. Every transaction recorded automatically, searchable by amount, time or customer, exportable at month-end. The agent keeps her ritual; she just stops doing maths in the dark.
What good agent tooling looks like
After hundreds of conversations, the list is remarkably consistent. Instant settlement on every transaction. A clear record of the day's business without a separate notebook. Dispute resolution measured in hours, not three-week email threads. Network resilience that degrades gracefully instead of freezing mid-transaction. And pricing transparent enough that an agent can tell a customer exactly what a withdrawal costs before they hand over their card.
None of these are luxuries. They're the difference between an agent who grows — adding a second terminal, hiring an assistant, opening a second stand — and one who gives up and goes back to selling phone accessories full-time.
The bigger picture
Agent networks are doing for financial access what mobile towers did for communication: leapfrogging the branch infrastructure entirely. The agents themselves are becoming entrepreneurs, employers and — increasingly — the most financially sophisticated people on their street. They deserve tools built with the same seriousness we'd bring to a corporate treasury product.
The neighbourhood bank isn't a metaphor. For millions of Nigerians, it's simply the bank. We're building for it accordingly.