From side hustle to registered business: the money moves that matter
The leap from "I sell things" to "I run a business" is mostly financial hygiene. The five moves that separate growing SMEs from stuck ones.
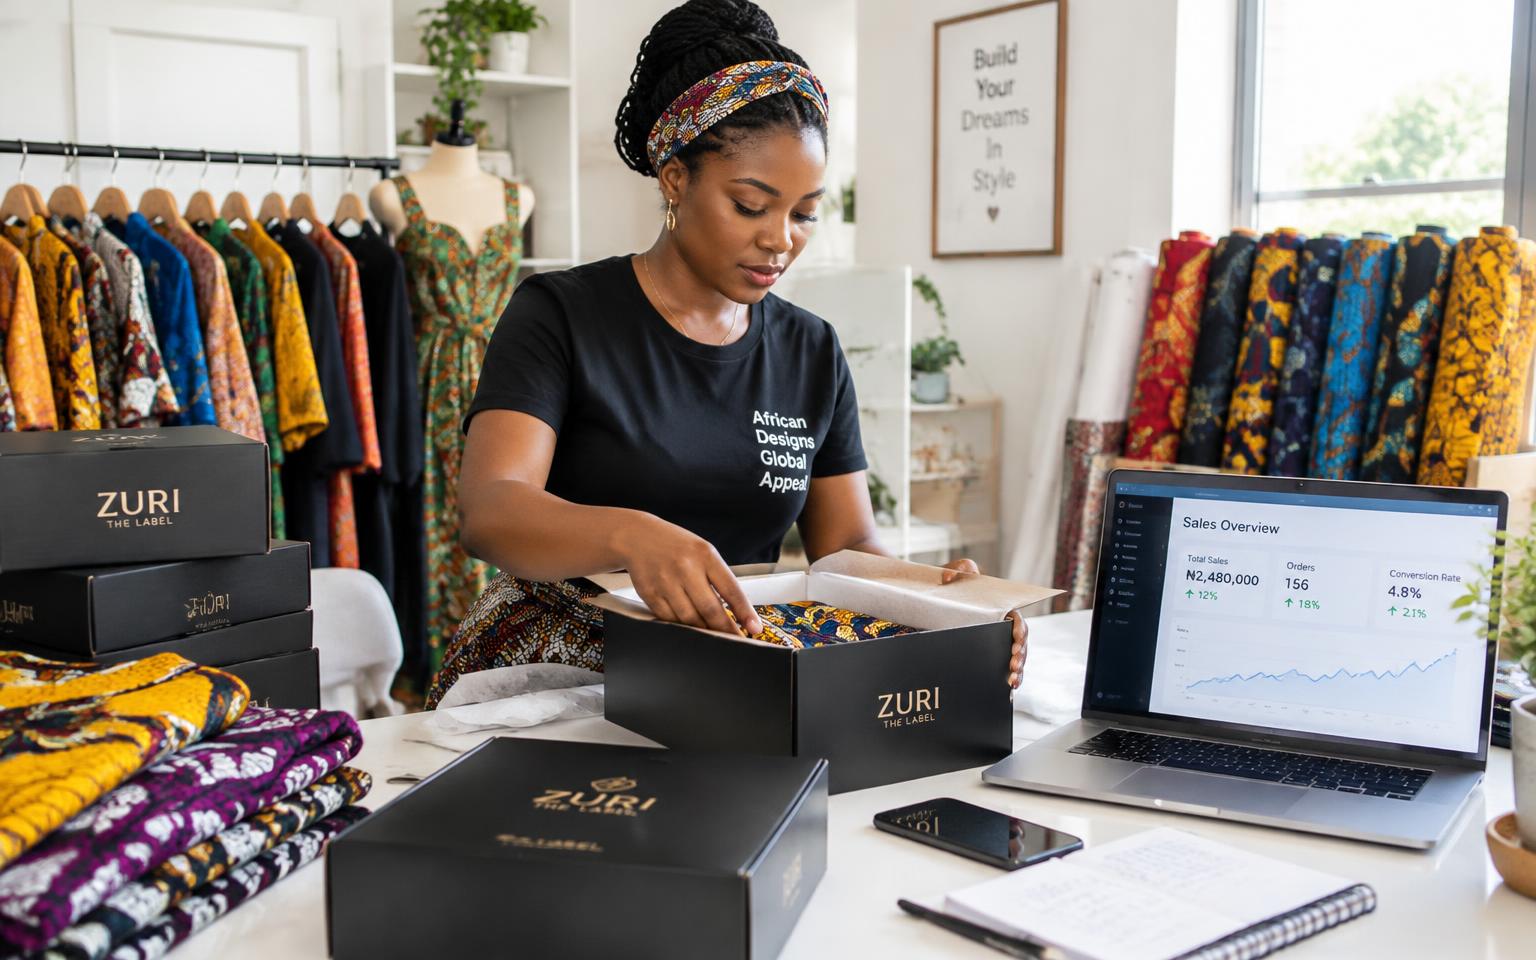
Nigeria has roughly 39 million small businesses, and the vast majority run entirely through the owner's personal account. It works — until it doesn't. The day you can't tell whether the business made money last month is the day the business starts making decisions you can't see.
The good news: the leap from "I sell things" to "I run a business" is mostly financial hygiene, not expensive consultants. These are the five moves we see separate the SMEs that grow from the ones that stay stuck — in the order we'd recommend doing them.
1. Separate the money
Open a dedicated business account and route every single business inflow and outflow through it. This one move does more for your clarity than any course or consultant. Suddenly "how is the business doing?" is a question with an answer, instead of an archaeological dig through transfers to your tailor, your landlord and your supplier, all mixed together.
Separation also changes how others see you. Suppliers extend terms to businesses with clean records. Marketplaces and corporate clients pay faster into business accounts. And when you eventually need credit, a clean twelve-month transaction history in a dedicated account is worth more than any pitch deck. With Pady Business it's a same-day setup, and your personal life stops subsidizing your business blind spots.
2. Pay yourself a salary
Even a modest, fixed monthly transfer from business to personal forces honesty. If the business can't afford to pay you, that's information — the kind you need early, not at the end of the year when the damage is done. It also stops the slow leak where "business money" and "chop money" blur until neither is tracked.
Pick a number the business can sustain in its worst recent month, not its best. You can always pay yourself a bonus in a good quarter; you can't un-spend a salary the business couldn't afford.
3. Keep records from day one
You don't need an accountant yet; you need every transaction categorized and exportable. When a bank, an investor or a tax officer eventually asks for your numbers, "give me a second" beats "give me three weeks" every time. Every Pady Business transaction is automatically categorized and exportable, so the record builds itself as you work.
The habit that matters most is the weekly ten-minute review: glance at the week's inflows and outflows, tag anything unusual, and note one sentence about how the week went. Ten minutes a week compounds into a business you actually understand.
4. Register when it unlocks something
CAC registration isn't a badge of honour — it's a tool. Register when it unlocks a corporate account, a contract that requires it, or a loan you actually need. A business name registration is cheap and fast; a limited company costs more but protects your personal assets and signals permanence to larger clients. Then keep your filings current; an inactive registration with three years of unpaid annual returns is worse than none.
5. Build a cash buffer
One slow month kills more small businesses than bad products do. Aim for one month of operating costs in a separate savings pot, then two. Boring? Completely. It's also the difference between a rough patch and a shutdown — and between negotiating with suppliers from strength or from desperation.
Build the buffer the same way you'd build personal savings: a fixed percentage of every inflow, moved automatically, locked loosely enough to reach in a real emergency but firmly enough to survive a tempting Friday.
The order matters
Notice the sequence: separate, pay yourself, record, register, buffer. Each step makes the next one easier, and none requires the others to be perfect. Start with step one this week. The businesses that make this leap rarely do it in a dramatic overhaul — they do it one boring, compounding habit at a time.