You already have a credit history — you just can't see it yet
Every transfer, bill payment and repayment is telling a story about you. How young Nigerians can turn everyday money behaviour into real access to credit.
Most young Nigerians believe they have no credit history because they've never taken a loan. That's not quite true. Your financial life — the salary that lands monthly, the bills you pay on time, the way you manage your balance — is already a track record. The problem is that for decades, nobody was reading it.
The old system was blind
Traditional credit scoring was built around formal payslips, collateral and existing loans — a club you couldn't join without already being a member. It locked out exactly the people whose disciplined money behaviour should have qualified them: traders with steady daily inflows, freelancers with years of client payments, young professionals who had simply never needed to borrow.
The result was a strange inversion: the people who managed money most carefully in cash were invisible to the system, while the people already inside it accumulated history almost by accident. Access to credit became hereditary — passed down through payslips and property rather than earned through behaviour.
Behaviour is the new collateral
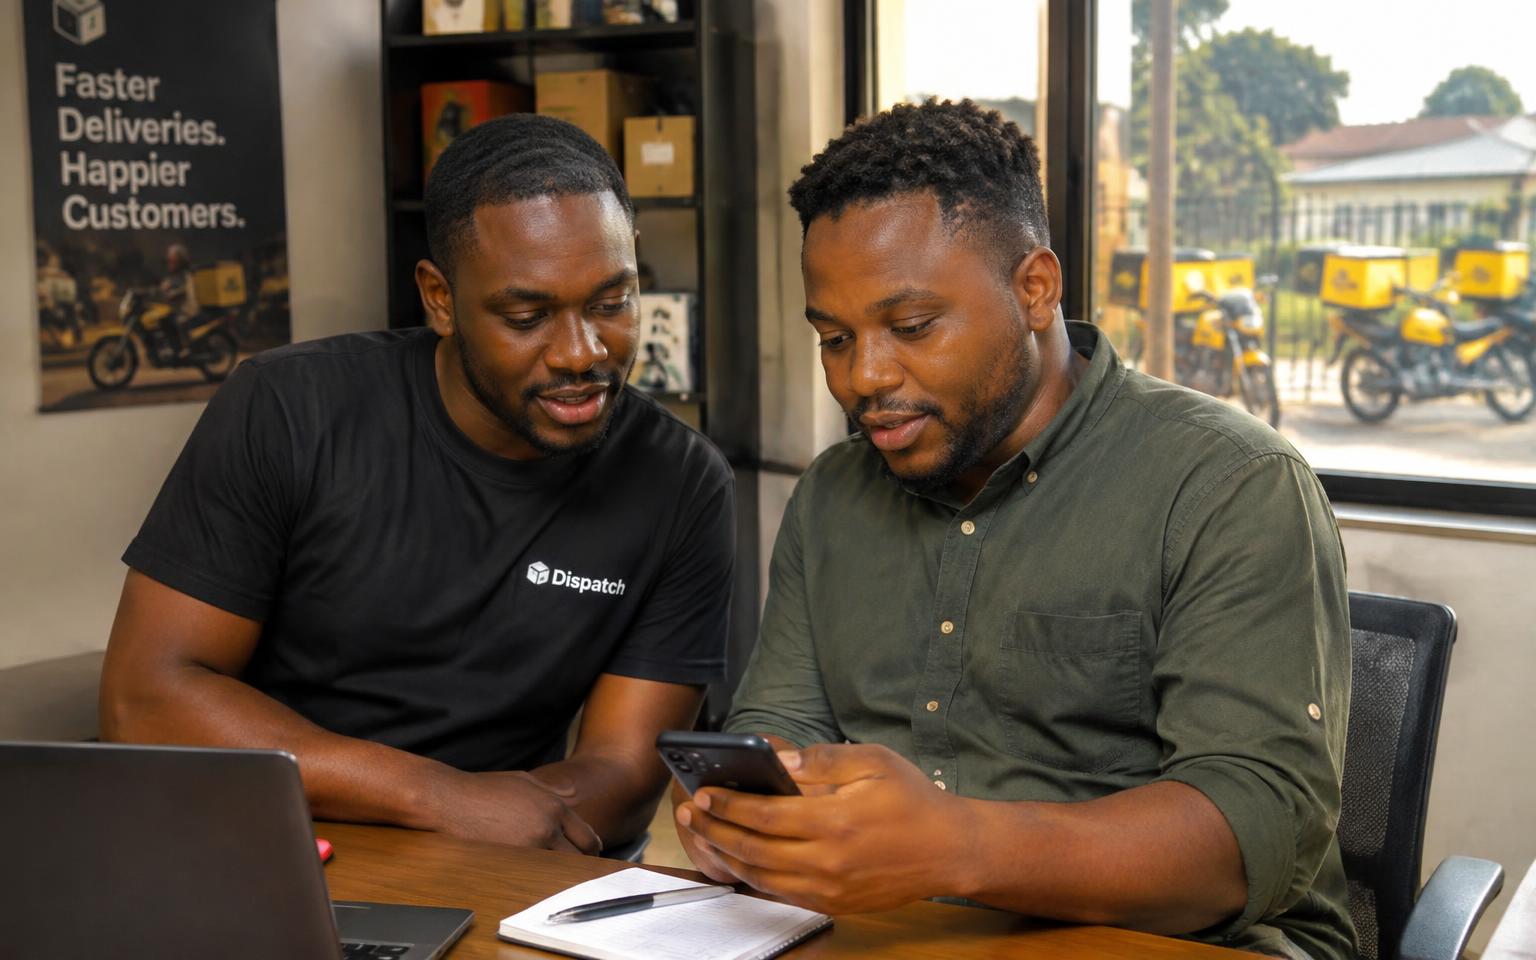
Modern credit looks at cash flow: money in, money out, consistency over time. A dispatch rider who receives payments daily and saves weekly is, behaviourally, a better credit risk than a salaried worker who is overdrawn every month. The data was always there — the tools to read it are what's new.
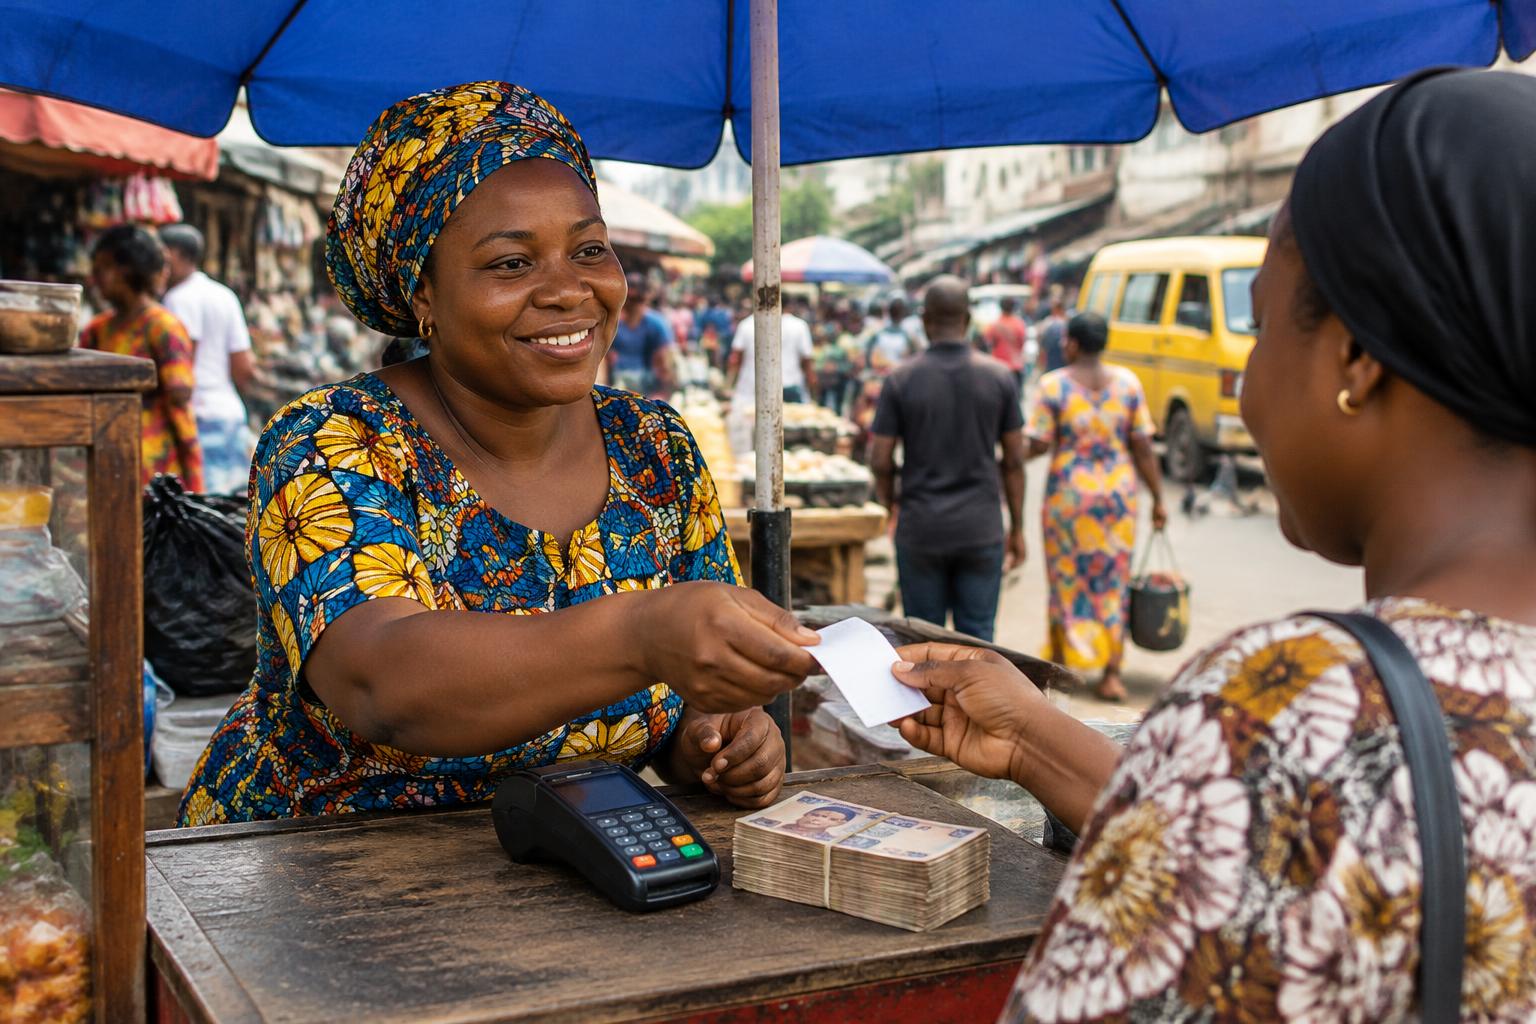
This shift matters beyond individual loans. When credit can see behaviour, entire segments become bankable: market women, gig workers, students with part-time income, SMEs with real revenue but no collateral. The informal economy stops being invisible and starts being legible — on its own terms.
How to build yours deliberately
Route your income through one account so your cash flow is visible and consistent — five scattered accounts look like noise, one steady account looks like a business. Pay bills from that account, on time, every time; a year of on-time utility and subscription payments is a quietly powerful signal. Keep a savings habit, even a small one — regular saving demonstrates surplus, and surplus is what lenders are really looking for.
And when you do take credit, take an amount you can repay comfortably and repay it early. Nothing builds a score like a clean, completed repayment — and nothing damages it like a small loan gone bad. The first loan isn't about the money; it's about the record.
What to avoid
Three traps undo years of good behaviour. First, loan stacking: juggling multiple app loans to repay each other is visible in your data and reads as distress. Second, guarantor carelessness: standing surety for someone unreliable makes their behaviour part of your record. Third, ignoring small defaults: a forgotten ₦3,000 loan app balance can weigh more than a clean year of banking. Check your record periodically and dispute errors — they happen more often than you'd think.
Where this is going
This is the bet behind Pady's approach to credit: your everyday money behaviour should count for something. As more of your financial life flows through rails that can read it, the question shifts from "what do you own?" to "how do you behave?" — and that's a far fairer question for a generation building wealth from scratch.
You've been building a reputation all along. It's time it started working for you.